Should you remodel your kitchen before selling? A dated kitchen rarely kills a sale. A half-finished one does it every time.
I’ve walked through houses where the seller pulled every cabinet door off, got an estimate for new ones, ran out of money, and listed anyway. Buyers price that mess at about double what it would cost to fix. They’re not wrong to.
The wider market shapes how buyers act, too. Redfin’s numbers for the four weeks ending October 25, 2026 put the national median sale price at $389,601, down 0.1% from a year earlier. The typical home sat 50 days on the market, and 21.5% of listings had cut their price.
If you’re weighing whether to remodel your kitchen before selling, every one of those numbers matters.
Should You Remodel Before Selling Your Home?
Appraisers don’t hand you a line item for a new kitchen. A home appraisal pulls value from recent sales nearby, then adjusts for condition. A remodeled kitchen can move your house to the top of what your street supports. It can’t push you past that ceiling, no matter what the receipts say.
That one fact changes the math for a lot of sellers.
Most homeowners I meet are remodeling for the wrong reason. A broker walked through, said the kitchen looked tired, and no one ran the numbers after that. Before you spend a dollar on cabinetry, weigh how much equity you hold and how fast you need to be out. Then ask yourself how much contractor chaos you can live with.
Timing is the part sellers brush off. Angi puts a midrange kitchen job, with new cabinets, counters and appliances, at four to eight weeks. That’s when things go right, and they go right maybe half the time. Stack the listing period and closing on top of that, and you’re looking at months before any money hits your account.
Three siblings called me a few years back after two agent listings expired with zero offers on the house their mother left them. I walked it on a Thursday. The kitchen still had its original 1978 laminate counters, and I knew right away this wouldn’t be an easy sell. Their dad’s old boat trailer was still parked in the garage. None of them lived within four hours of the property. The thought of running a remodel long distance had stalled them for a year.
They sold as-is instead and split the proceeds that quarter. Not every seller should remodel, and a listing pitch tends to skip that part. Maybe distance, a tight deadline or a repair list you can’t fund is in the way. A direct buyer like House Buying Heros will give you a number on the house as it stands today.
Which Renovations Give You the Highest ROI?
Spend more, get more back. Kitchen budgets break that rule harder than almost any project in real estate.
The 2025 Cost vs. Value report priced a midrange minor kitchen remodel at $28,458 and credited it with $32,141 in resale value. That’s about 113% of the cost. Go big and the return falls apart. An upscale major remodel ran $164,104 and got back about 36%. At that point you’re paying for a lifestyle. Keep in mind those resale figures are estimates from real estate pros, so treat them as a guide.
Scope drives the return far more than spend does.
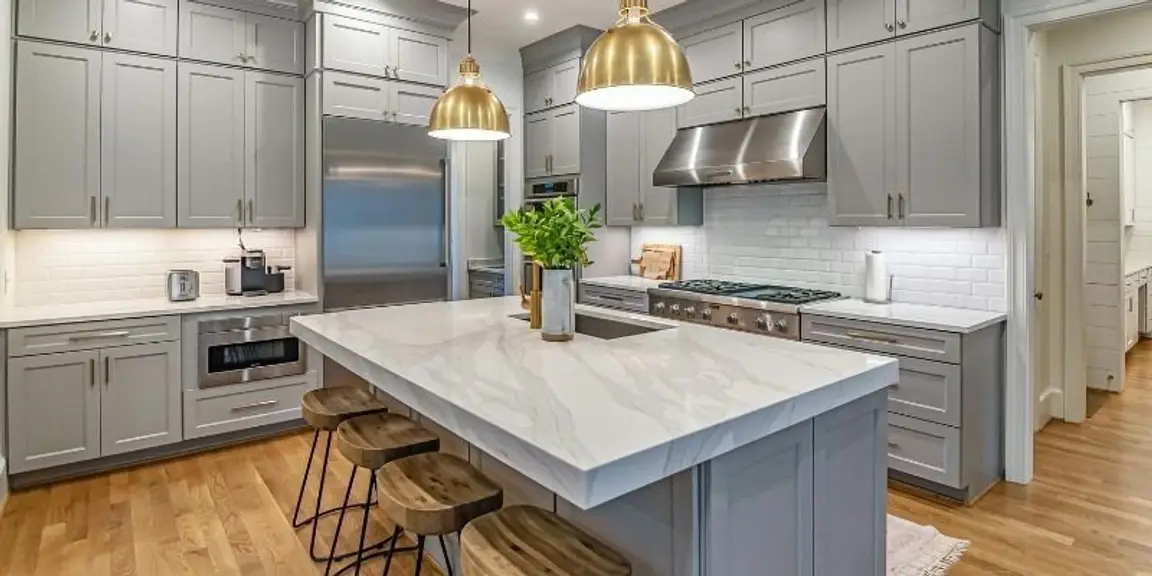
Minor work usually means refacing or painting cabinets, new countertops, fresh hardware and a new sink and faucet. A mid-range kitchen appliance or two often rounds it out. Once you move a wall or a plumbing line, the project jumps into a pricier tier with worse math. Premium appliances return less than mid-range ones, which surprises sellers who just priced a built-in fridge.
Where does money go furthest? Often outside the kitchen. In that same report, a garage door replacement returned 268% and a steel entry door 216%. A new asphalt roof recouped only 68%, yet fixing one an inspector would flag protects your whole sale price. I’ve watched homebuyers forgive laminate counters without a second thought, then walk away over one stained ceiling they were sure meant a roof leak.
Here’s one more number to hold onto. The 2026 Houzz Kitchen Trends Study, which surveyed homeowners in July 2025, found a median spend of $20,000 on minor kitchen updates. That’s real money for a pre-sale refresh, and you don’t see it again until closing day.
My rule of thumb after hundreds of buys: if your kitchen works and it’s clean but dated, paint and hardware beat demolition. If the kitchen is broken, sell as-is and price for it. If you’re leaning that way, here’s what selling a Garland home that needs repairs looks like without fixing a thing first.
How Does a Home Equity Line of Credit Pay for Renovations?
On November 4, 2026, the average APR on a $100,000 HELOC at 60% loan-to-value was 7.50%, according to Curinos data published by Forbes. That’s the going cost of turning equity into renovation cash without touching your first mortgage. A point either way can decide whether a project pencils out.
A home equity line of credit works like a credit card secured by your house. The lender sets a limit based on your equity, credit and debt load. During the draw period you pull only what you need and pay interest on what you’ve drawn. Pay a contractor $8,000 for cabinet refacing, and that’s the balance building interest.
Most HELOCs carry variable rates tied to the prime rate, so your payment moves when prime moves.
Plenty of owners are using them. HELOC originations through July 2026 ran 6.6% ahead of 2025, Bankrate reports, citing Equifax credit data. Low-rate first mortgages are a big reason. No one wants to refinance a 3% loan to pay for countertops.
For a seller, though, the line gets paid off at closing out of your proceeds. Every renovation dollar you borrow comes off your net, plus interest for every month the project and sale take. Borrow against a property you plan to list within a year, and you’re betting the remodel adds more than it costs. A minor refresh can win that bet on paper, although commissions, carrying costs and months of interest tend to shrink the margin faster than most sellers plan for.
Timing cuts against you too. Underwriting, appraisal and funding on a HELOC take weeks. Then your contractor needs weeks. If you’re selling because of a job transfer, a divorce or payments you can’t carry, that sequence doesn’t fit. A cash offer skips the borrowing question, and House Buying Heros can help you see what one looks like.
No Income? How Do You Still Qualify for a HELOC?
For years I told retired sellers a HELOC was off the table without a paycheck. I was wrong about that.
Lenders outside the conventional box qualify borrowers a few ways. Asset depletion is the one I see most with retirees, and it works best for people with large investment accounts. The lender totals your eligible liquid assets and applies a discount by asset type. Then it spreads the result over a set number of months to create a monthly income figure. One California lender, Lendia, calls a 120-month divisor the norm, though the formula shifts from program to program. Your savings stay invested. They’re just counted.
Self-employed owners often take the bank statement route, where deposits over 12 or 24 months stand in for tax returns. Landlords can sometimes qualify on the rent a property collects instead of personal income. There are no-doc lines too, and lenders offset the thin paperwork with stricter credit and equity rules.
Every one of these programs runs higher than a standard HELOC. Ask any lender for the divisor, the loan-to-value cap and the reserve requirement in writing before you spend time on an application.
This is where I’d push back on the usual advice. Picture an owner with no income who takes a variable-rate line to remodel a kitchen before selling. That’s stacking risk on risk. If the property sits longer than the agent projected, you’re paying a new debt out of savings. Sellers settling an estate or living on a fixed income get squeezed hardest.
Would you take that loan if the house didn’t sell for nine months? If the answer makes you uneasy, list the house as it stands and keep your cash where it is. Homeowners in that spot can also see how we buy houses in Carrollton with cash offers, no HELOC required.
What’s on the Checklist for Selling a House?
A few things have to happen before the sign goes in the yard.
Start with the title. Pull your latest deed and confirm the names on it match the people signing. Probate issues, old liens and unrecorded releases tend to surface at the worst moment. Your county clerk’s office can tell you what’s recorded against your property and what copies cost.
Next comes your number. Look at what comparable homes closed for in the last 90 days, and ignore what neighbors listed for in spring. Then build your cost sheet with agent commissions, title charges, prorated taxes and any concessions a buyer asks for after inspection.
Disclosures come after that, and the rules vary by state. Most states require written disclosure of known material defects, so check with your state’s real estate commission before you rely on a blog or a forwarded email.
On the property itself, deep clean and declutter. Handle deferred maintenance an inspector will flag anyway, and make sure every faucet, outlet and appliance works. Photos sell the house before a buyer ever opens a lockbox.
A woman reached out to us while settling her father’s estate. She was three months behind on his mortgage with an auction date already on the calendar. The house needed a new kitchen, two bathrooms and a water heater. She needed the debt gone and a firm closing date. We closed on her timeline and the auction came off the books, and in cases like hers, no one picks out cabinet colors.
Her situation isn’t rare. If you’re in North Texas, we buy houses in Dallas, and we’re also cash home buyers in Plano and nearby towns. When the clock is the real problem, the countertops can wait.
Frequently Asked Questions
Is a Kitchen Remodel Worth It for Resale?
A modest refresh often pays for itself or comes close, as long as the scope stays cosmetic and the layout stays put. A full gut renovation almost never returns what you put in. If you’re selling within a year, run the budget against your expected sale price first. Every dollar you spend comes out of your proceeds.
What Kitchen Cabinet Colors Are Going to Look Dated in 2026?
High-gloss gray and stark, cool whites have both lost ground to warmer whites, soft greige and natural wood tones. Dark navy and deep black cabinets still work in the right design, though they can feel trendy in a small kitchen. Buyers forgive a neutral they’d repaint far faster than a bold color they’d have to strip.
What Adds the Biggest Value to a House?
Exterior projects top most return studies, led by garage doors, entry doors and siding. A sound roof, HVAC, windows and basic landscaping protect your price, since buyers and appraisers treat them as baseline condition. Kitchens and baths matter most when they’re clean and working, even when they’re plain.
Should I Fix Everything Before Listing?
No. Fix what’s unsafe, what leaks and what an inspector will write up in bold. Leave the rest alone and price for it. Buyers tend to discount visible flaws less than sellers expect, and that discount is far smaller than the cost of chasing perfection on a deadline. It also helps to know how to sell a house as-is without an inspection and what you’d still need to disclose.
How Fast Can I Sell Without Making Repairs?
A cash sale often closes in one to two weeks, depending on title. The tradeoff is price. You give up some equity for speed, certainty and the chance to skip showings, repairs and financing contingencies. Whether that trade makes sense depends on your timeline and how much work the house needs.
The Short Version
You could spend weeks agonizing over cabinet colors, and it’s the decision least likely to change your outcome. If you’re staying put, pick a warm neutral you’ll still like in five years. Whether you remodel your kitchen before selling or leave it alone, the real question is whether the kitchen should be your problem at all.
Want to skip the renovation math? It costs nothing to see what a straightforward cash offer looks like. Get the number, sit with it and compare it to what a listing would net you after repairs and commissions. When you’re ready, contact us and ask for your number. No pressure either way.
Helpful Texas Blog Articles
- How to Sell a Condemned House in Texas
- Can You Sell a House As-Is Without Inspection
- How to Sell a House That Has Flooded in Texas
- Can You Sell a House With Mold in Texas
- How to Sell a House While Living in It
- How Capital Gains Tax Works When You Sell a Rental Property
- Can Medical Bills Take Your House in Texas
- Should You Remodel Your Kitchen Before Selling Your House